Ask any scenario. Know every risk.
Instant guideline answers and a live pipeline brief. Built for the loan officer who closes deals.
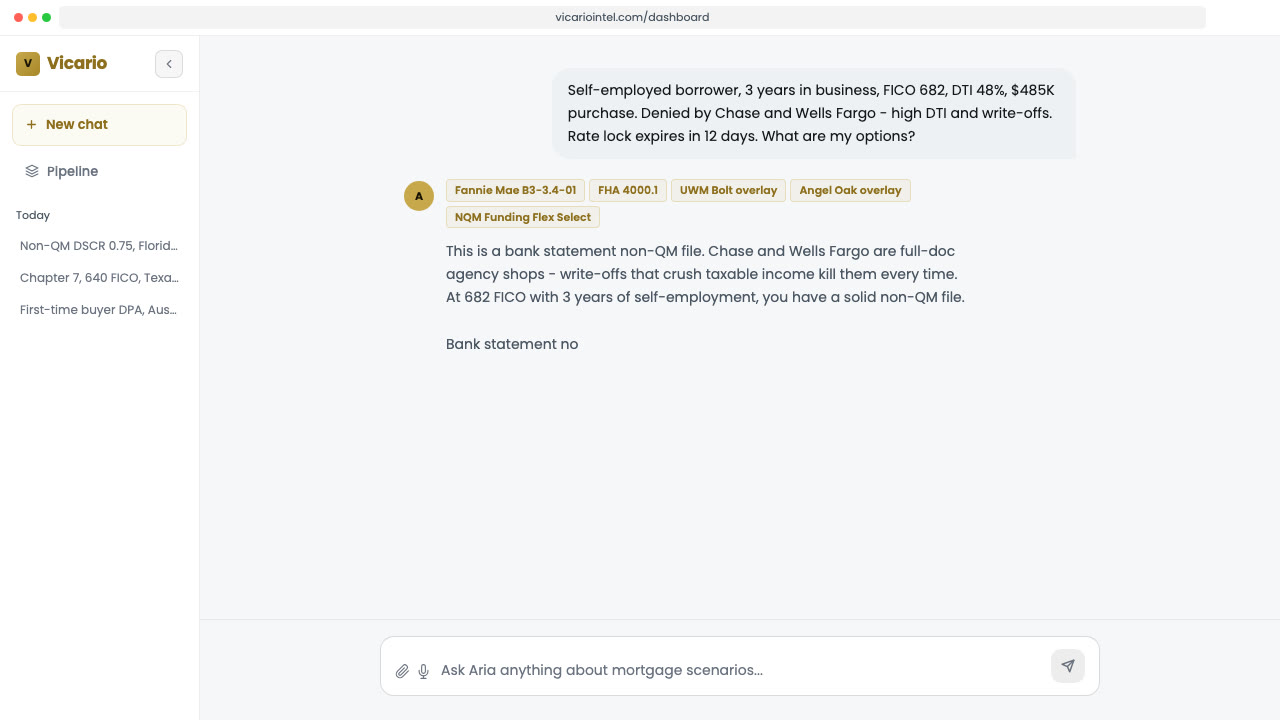
Purpose-built for mortgage.
Not a general chatbot.
Every agency rule. Cited by source.
Fannie Mae, Freddie Mac, FHA, VA, and USDA through 2026. Every answer includes the guideline name and section.
The 2026 FHA floor loan limit for a one-unit property is $541,287, set at 65% of the conforming baseline. High-cost ceiling is $1,249,125.
My First Texas Home
ONE Mortgage
FL HFA Preferred
Every state. Every program. Current terms.
All 50 state Housing Finance Agencies: income limits, structure, and assistance amounts, updated as programs change.
Know who can do the deal before you call.
200+ lenders with DSCR, bank statement, foreign national, and agency overlays.
Who needs your call. Before you ask.
Per-deal cards with the exact reason and one action to take today. Stall detection flags files stuck 7+ days.
Martinez Rate lock expires in 3 days.
Patel Stale 28 days. Check in before the 30-day flag.
Chen In underwriting. On track.
Actively maintained. Not autonomously drifting.
Every query sharpens the knowledge base. Gaps get flagged, researched, and verified by a human before they ship.
How Aria avoids guessing
Every answer cites its source. Guideline name and section, not a general summary.
Uncertain answers name the next step. "Call the AE. Verify with the HFA." Not a guess dressed as a fact.
Knowledge gaps are human-verified. Before any update ships, a person checks it against the primary source.
Updated continuously
Gaps flagged, verified, and shipped
From scenario to answer
without touching a handbook.
Describe the scenario.
Type any borrower situation in plain language. Self-employed, DSCR, employment gap, non-warrantable condo. Aria reads the context.
Aria reasons through it.
Aria cross-references agency guidelines, 50-state DPA eligibility, and lender overlays specific to your state and scenario type.
You get a research answer.
A specific program, a specific lender to call, and exactly what to verify before you send the file. You make the call.
What loan officers say.
Real outcomes from licensed MLOs using Aria on real files.
“Aria surfaced a HELOC solution I hadn’t considered. Funded the deal within a few days and put several thousand dollars in commission in my pocket.”
Jason Brothers
Loan Officer, Sunny Hill Financial · NMLS #829954
“For an experienced MLO well-versed in risk assessment and source underwriting guides, Aria is useful for bird-dogging solutions on complex files.”
C.J. Rice
Senior Instructor, LoanOfficerSchool.com
“None yet match the tool that you or others in your space provide yet.”
David Reinholtz
Founder, LoanOfficerSchool.com
Simple pricing. No per-query fees.
One flat monthly rate for individuals. Custom arrangements for teams and platforms.
Individual
Most popularLess than one closed loan's marketing spend. Unlimited scenarios, all year.
For licensed MLOs who handle complex scenarios daily.
- Unlimited Aria queries
- All 50-state DPA programs
- 200+ lender overlays and pipeline analysis
- Lender routing by deal type
- Agency guideline intelligence (Fannie, Freddie, FHA, VA, USDA)
- Confidence-calibrated responses
Team
5 seats · $39.80/seat · see all block sizes
- Everything in the individual plan
- Dedicated onboarding
- White-label ready
- 5, 10, 20, or 50 seat blocks
Need 50+ seats? Contact us
Why $49
Category alternatives stop at agency guidelines. Vicario adds named non-QM overlay routing across 200+ lenders, all 50-state DPA depth with current income limits and program terms, and pipeline intelligence that surfaces which deal needs your call today. The $8 and $12 tools do not include any of that.
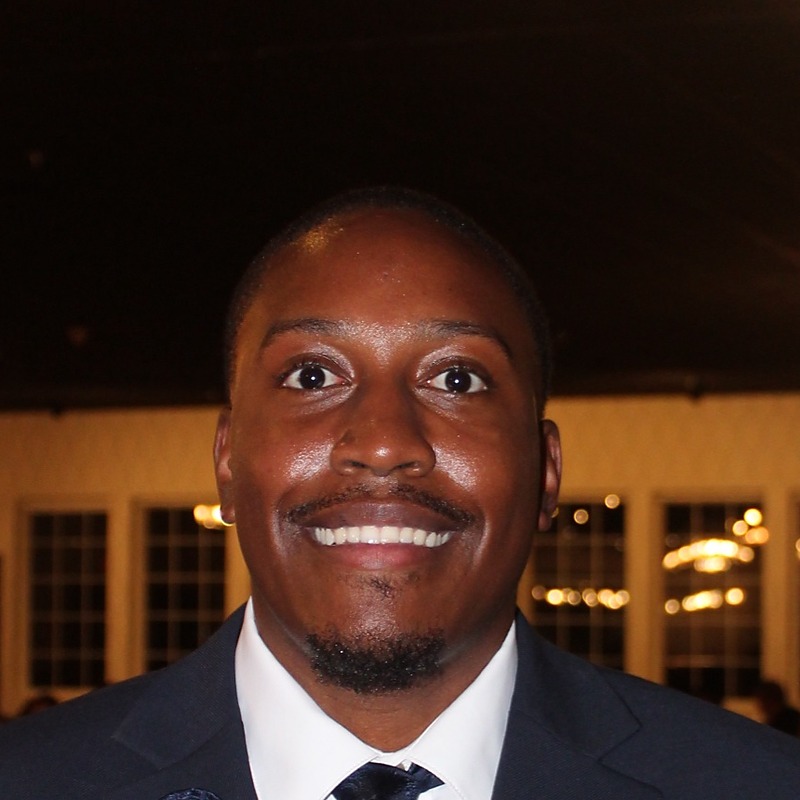
Why I built this
I was researching what it would take to get my mortgage license when I started spending time in the Facebook groups where loan officers talk through live deals. The same question came up constantly: who can do this? DSCR at 0.75, employment gap, non-warrantable condo. LOs were burning hours on the phone with AEs and posting cold into groups while borrowers waited. The same feeds were flooded with competing LOs advertising for the same clients.
It was clear the problem wasn't a shortage of originators. It was a shortage of answers. I stopped pursuing the license and started building Aria instead. If I could put an experienced underwriter's routing knowledge into every LO's pocket, it would reach far more borrowers than I could ever serve originating loans myself.